A personal finance planner and money school, designed from conversations about money worries.
An offline desktop app that turns a bank statement into a budget, shows how healthy your finances are in plain language, and teaches personal finance through short guides linked to your own numbers.
Four iterations, each one starting with a critique of the version before it
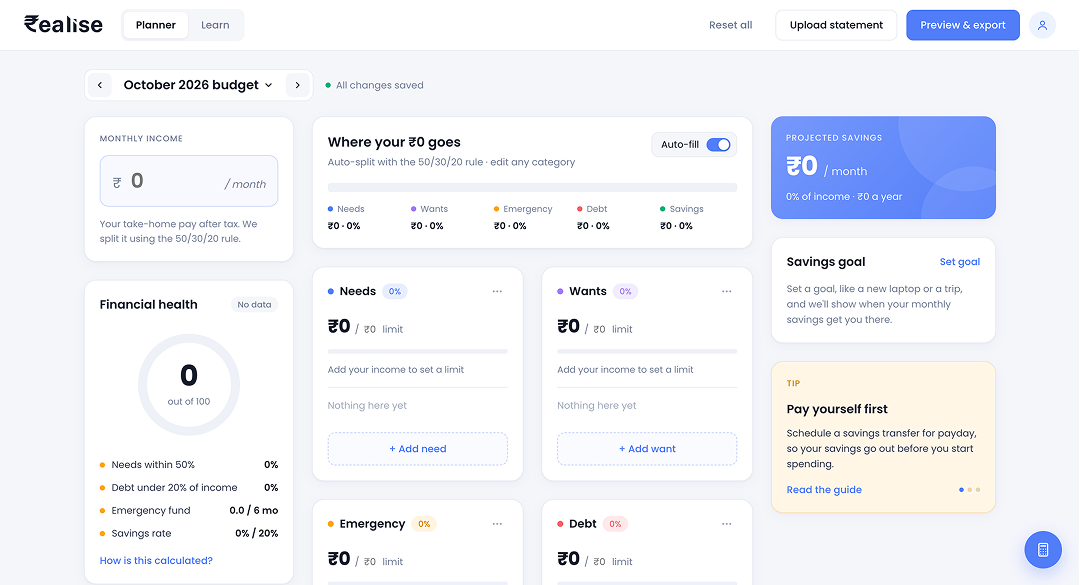
Manual planner
It worked, but felt like a notebook.
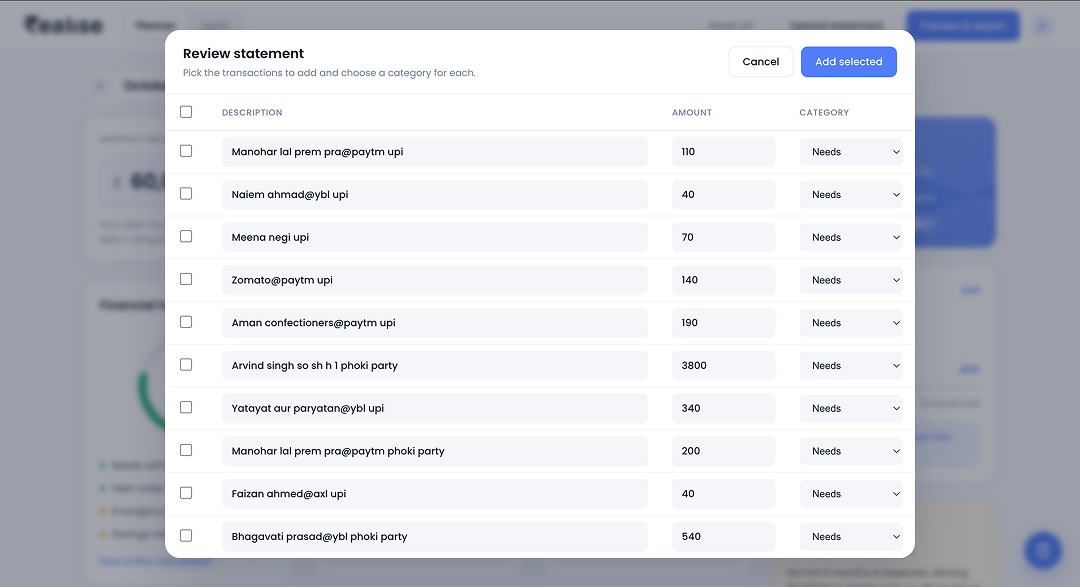
Statement upload
Became the main way in, removing the effort that makes people give up on budgeting.
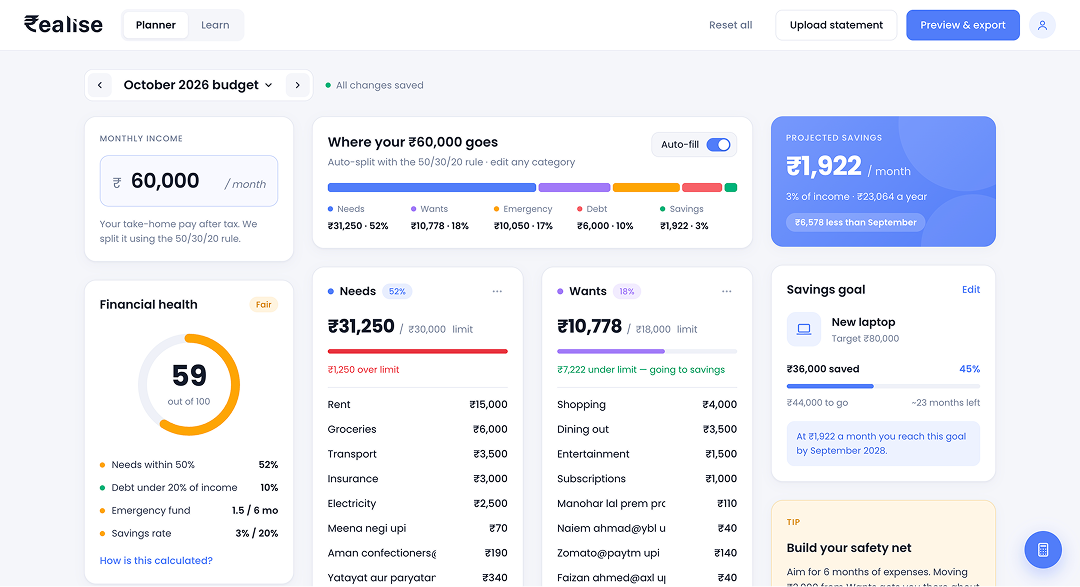
More to explore
A tool that did one job became one you can dig into.
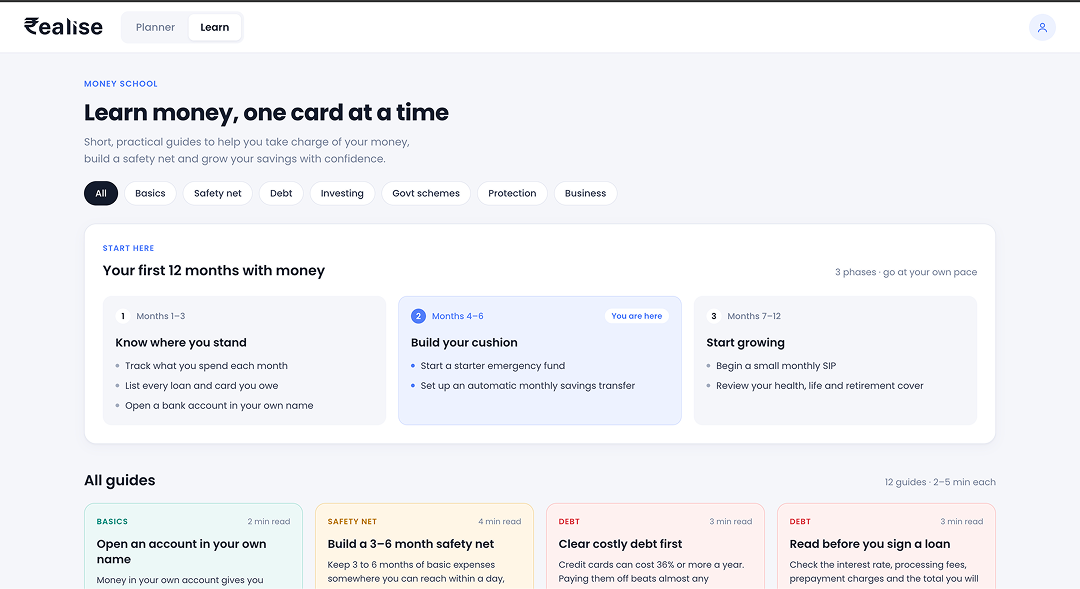
Money school
Financial education for women, linked to their own plan.
Salaries disappeared by mid-month, and investing felt “not for me”
Friends and people around me kept bringing up the same worry: money. Savings never happened, and investing felt confusing.
Young earners don’t know where their money goes or whether they’re doing okay, and the advice they find is generic, full of jargon and disconnected from their real numbers.
| Option | Gap |
|---|---|
| Notebooks / spreadsheets | Manual, tedious, no benchmark for “good” |
| Budgeting apps | Assume financial knowledge; often need you to link accounts online |
| Finance contentYouTube / Instagram | Generic and separate from your own budget, so nothing gets acted on |
Everyone was worried about money; few had a system
Informal conversations with 7 people (aged 22–28: students, first-jobbers and young professionals) about how they manage money, what worries them and what they’ve tried.
- Almost everyone was worried about their finances, but few had a system.
- Some participants suggested what a solution might look like. These conversations sparked the product idea.
“I check my balance and just hope it lasts till the 30th.”
Desktop and offline
Money data feels personal; people wanted it kept on their own device.
Simple to start
No sign-up and no complex setup.
Show what “okay” looks like
Numbers need context.
If people can see their income split across categories, they’ll spend more mindfully
- Income input
- Four categories (Needs, Wants, Emergency, Debt), each with a list of items you can edit
- Projected savings and a simple health score
- A savings goal with progress
“It works, but this is something you could do in a notebook.”
Entering every expense by hand is the exact habit people give up on. The product worked, but it wasn’t saving any effort, so it wasn’t solving the real problem.
Decision: change how the data gets inA budget that fills itself from your bank statement
Upload is the main action
Placed prominently in the header.
A review table
Descriptions are cleaned up (UPI and reference codes removed). Tick the rows you want, pick a category, and they flow into the budget.
Manual entry stays
Now secondary, for cash spends or items the statement misses.
Review before anything is added
Automatic categorisation can be wrong, so the user stays in control of their budget.
Change priority, don’t delete
Manual input still serves some users. It just stopped being the default.
A feature can work and still not be worth using. Judge a product by the effort it saves, not by whether it functions.
Simple for people who want the basics, with depth for the curious
50/30/20 Auto-fill
Limits to aim for. Edit one and Auto-fill turns off, so you’re never locked in.
Allocation bar
“Where your ₹60,000 goes”: the whole month at a glance.
Plain-language status
“₹8,000 under limit, going to savings” reads like a friend, not a spreadsheet.
Health score, 0–100
Four checks with partial credit, and “How is this calculated?” so users can trust it.
Emergency fund tracker
“1.8 of 6 recommended months” makes the most-skipped habit visible.
Goal with a finish date
“You reach this goal by December” turns saving into a deadline.
Tips from your numbers
“Move ₹2,000 from Wants, get there ~9 months sooner.”
Month-by-month budgets
“vs last month” comparison; a new month copies the last one.
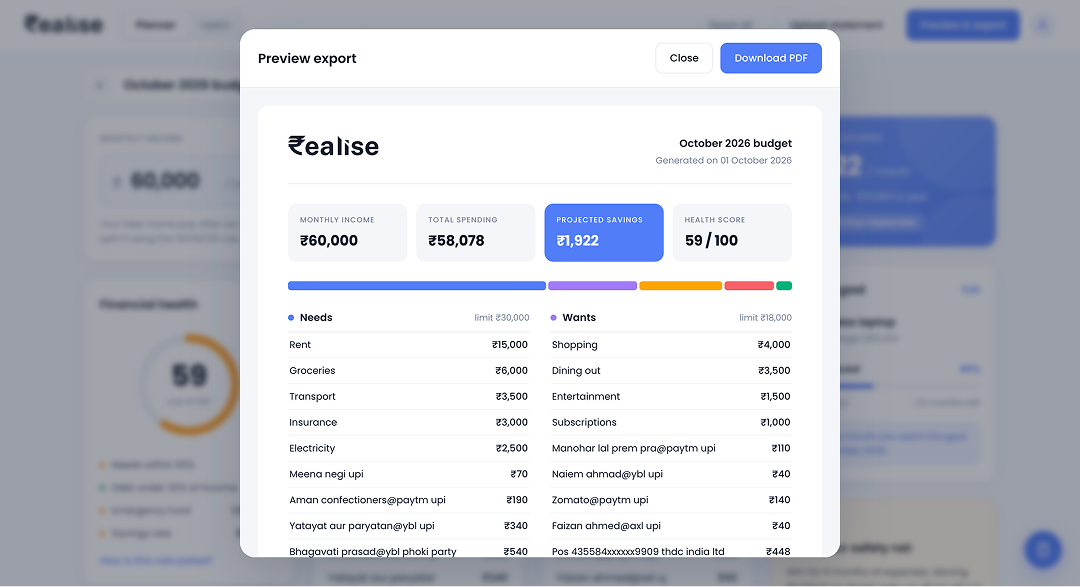
PDF export
Keep or share a clean summary.
Many women I know were never taught about money. A budget alone can’t close that gap.
Turn learning into doing: every guide should end with something you can apply to your own plan.
Responsible design
A clear “for education, not financial advice” disclaimer, and a note that government rates change every quarter, with a prompt to check the latest rate.
- A library of 12 guides across 7 topics, with filter chips and topic colours
- “Your first 12 months with money” roadmap that marks where you are, based on your budget
- Topics for women’s real situations: an account in your own name, Sukanya Samriddhi, MUDRA and Stand-Up India loans, insurance
- Interactive guides with calculators that end in “Add as goal”
- Compare options at a glance: savings account, liquid funds, PPF, index funds, gold
- Connected both ways: planner tips open guides; guides send actions to the planner
Every choice gave something up, on purpose
| Decision | Trade-off | Why I chose it |
|---|---|---|
| Offline, data stays on the device | No sync across devices | Privacy and trust came up as the top concern |
| 50/30/20 as an editable default | Doesn’t fit every situation | Beginners need a starting point; others can override it |
| Emergency & Debt stand alone | More categories to understand | The two habits that most affect financial health |
| One savings goal at a time | Less flexible | Keeps focus; the app confirms before replacing a goal |
| Short guides (2–5 min) | Less depth | Easier to finish, and each one ends in an action |
| Review before importing | One extra step | The user stays in control, so the data is accurate |
Friendly type and one colour per category, used the same way everywhere
Poppins: rounded and friendly, which makes money feel less intimidating.
One primary blue, plus a fixed colour per category across bars, badges and cards.
Three columns: Inputs & health → Allocation & categories → Savings, goal & tips. One column on mobile.
A custom ₹ealise wordmark with the rupee sign built into the name.
The idea came from listening, and the best critique came from me
- 6 of 7 people set up a budget in under 3 minutes
- The people I first spoke to said the plain-language status was the first money view they actually read
- 3 of the 7 started an emergency fund within a month
- Usability testing with the original participants
- More statement formats and smarter auto-categorisation
- More interactive guides, and multiple savings goals
- Start with people, not featuresThe idea came from listening.
- Critique your own work honestly“This could be a notebook” was the most valuable feedback I got.
- Change priority instead of deletingManual input survived, just not as the main way in.
- Simple, with depth for those who want itExplorable without being overwhelming.
- Design for who’s left outThose who most need money knowledge are often the least likely to be taught.